
Before diving deeper into company specific, it’s important to understand where Antelopus Selan Energy sits in the Oil Industry.
The oil & gas industry can broadly be divided into three layers -
Upstream: Find or develop oil and gas fields, drill wells and produce hydrocarbons.
Midstream: Transport and store them through pipelines, terminals and storage infrastructure.
Downstream: Refine crude oil into products such as petrol, diesel and aviation fuel and sell them to consumers.
Companies such as ONGC and Oil India are primarily upstream players, while companies such as IOCL, BPCL, HPCL and Reliance have significant downstream operations.
Antelopus Selan Energy sits almost entirely in the upstream segment.
The company develops oil and gas fields, drills wells, and produces crude oil and gas. Crude oil is primarily sold to refiners such as IOCL, while gas is sold to nearby industrial customers.
India’s Oil Paradox: More Demand, Less Supply
India currently imports roughly 90% of its crude oil. In FY26, the import bill touched $134.7 billion. At the current run rate, FY27 could land near $180–190 billion. Domestic production, meanwhile, is heading the wrong way. ONGC’s output fell from 19.21 million metric tonnes in FY24 to 17.80 MMT in FY26. The country’s structural need is straightforward: produce more at home, or keep writing larger cheques to the world.
The government’s response has been aggressive opening of “no-go” offshore areas, launching the Samudra Manthan scheme with an ₹84,000 crore outlay, and pushing for deep water exploration. But here’s what gets missed in the noise: not every solution requires a new basin or a billion-dollar offshore rig. Sometimes, the answer is sitting in a field that someone else walked away from because it was “too small to matter.”
The Business Model - Developers not Explorers
In oil and gas, there are two completely different games -
Exploration is asking: Is there oil down there? The odds are terrible - maybe one in five wells works. When it fails, you lose everything.
Development is asking: We know the oil is there - can we get it out profitably? The risk shifts from geology to execution.
Antelopus Selan deliberately refuses to play the first game of exploration.
Every asset they own is a discovery i.e. someone, usually ONGC or a small player before them, already drilled it, confirmed hydrocarbons, and then left it stranded. Why? Three reasons that repeat across their portfolio:
Too small for the giants. A field adding 500 barrels per day doesn’t move the needle for ONGC. It sits on the shelf for decades.
No pipeline. You can produce oil, but if there’s no evacuation route, you can’t sell it.
The previous owner ran out of money. Small players found something, couldn’t fund the next stage, and walked away.
When Cash Met Runway: The Merger Story
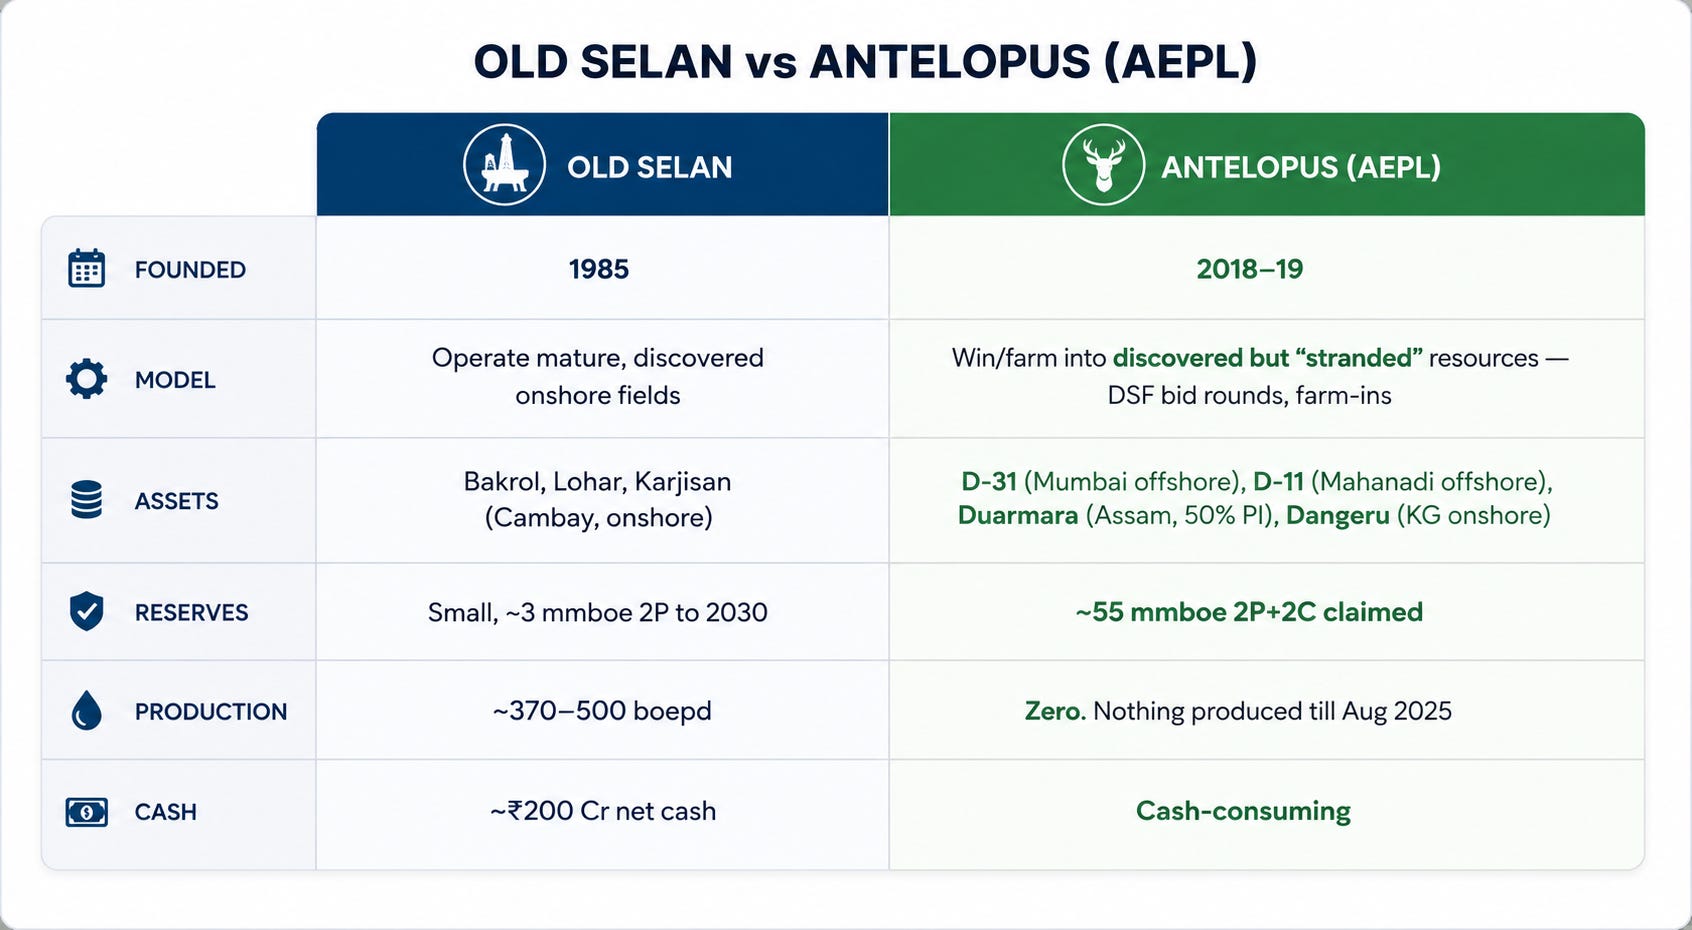
The company we see today, Antelopus Selan Energy didn’t exist three years ago. It was two separate entities that needed each other.
Selan Exploration was a 1985-era company with three small producing fields (Bakrol, Lohar, Karjisan Oilfields) in Gujarat’s Cambay basin. For twenty years, it did almost nothing- revenue barely moved, production stagnated at ~370 barrels of oil equivalent per day (boepd) with claimed reserves of 3 million barrels of oil equivalent (mboe) , and it sat on ₹200–220 crore of cash. A classic cash box with a sleeping asset.
Antelopus Energy was the opposite. Incorporated in 2018, it had won blocks in the DSF bidding rounds - offshore Mumbai (D-31), Mahanadi (D-11), onshore Assam (Duarmara), and Krishna-Godavari (Dangeru). It claimed ~55 million barrels of oil equivalent in reserves. But it had zero production and was burning cash.
This led to a Perfect Merger with strong synergy.
In 2022, Blackbuck Energy Investments backed by Oaktree Capital acquired control of Selan. By July 2025, Antelopus merged into its listed subsidiary. The combined entity, renamed Antelopus Selan Energy, now had something rare: cash flow from legacy assets and optionality from large undeveloped reserves.
Post Merger - A Complete Change in strategy.
A new management team with experience from companies such as Cairn and Vedanta came in - the team that ran India’s most successful private onshore oil asset. The company started drilling more aggressively and looking at ways to increase production from its existing fields.
The transformation can be seen in one simple number:
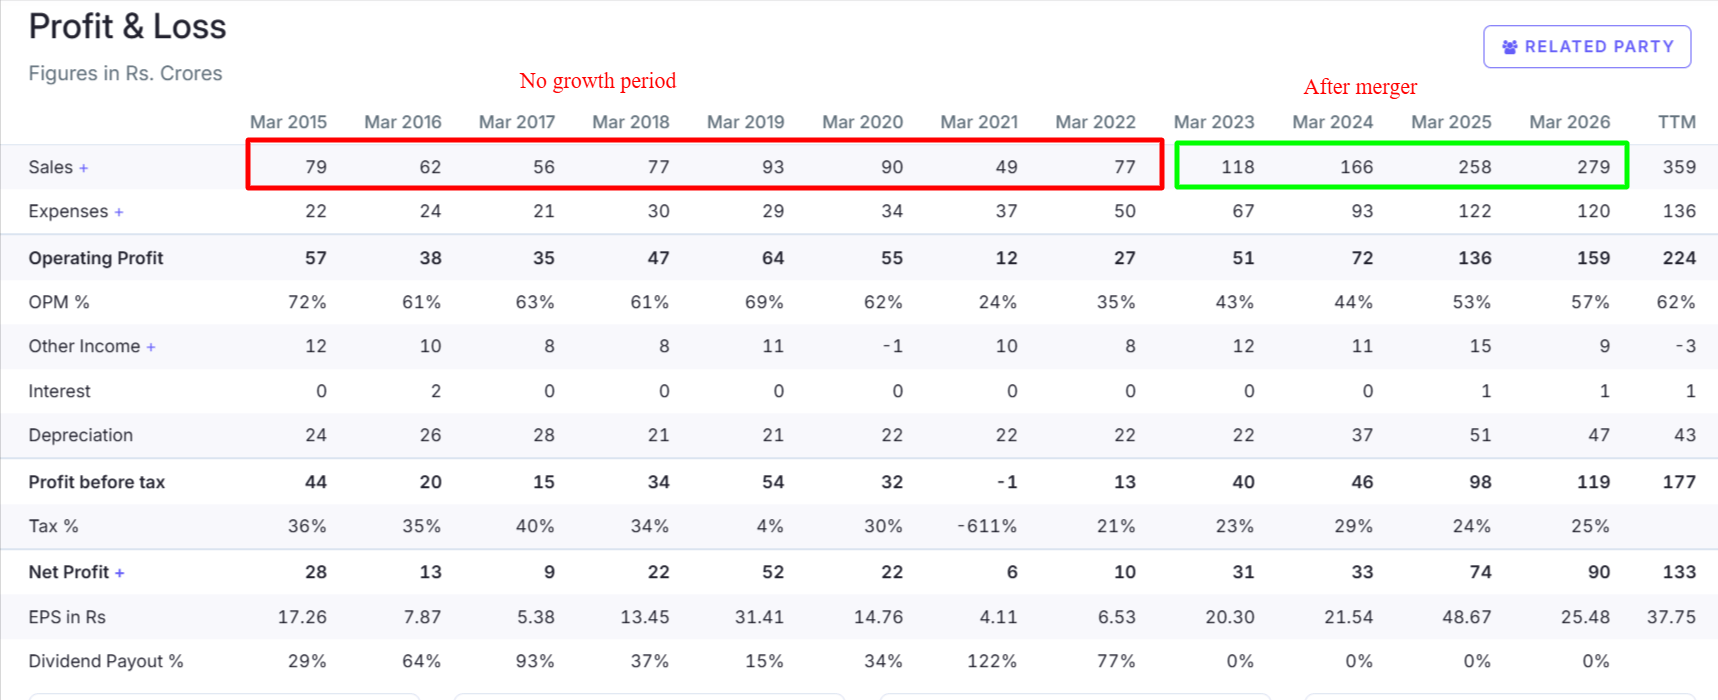
Production increased from around 511 boepd in FY23 to 1,355 boepd in FY26.
The March 2026 exit rate was around 1,880 boepd.
This is important because the growth has not primarily come from simply benefiting from higher oil prices. In fact, FY24–FY26 growth was largely volume-driven, while realisations declined.
That makes the story more operational than commodity-price driven.
The merger brought several additional assets onto the listed company’s balance sheet, including assets in Assam, Andhra Pradesh and offshore fields in Mumbai and the Mahanadi Basin.
This changed the nature of the company.
Before the merger, the story was largely about developing a handful of small producing Gujarat fields.
After the merger, it became a combination of:
Existing production + near-term drilling opportunities + a much larger undeveloped resource base. The company now has a portfolio spanning multiple basins and geographies.
From FY23 after successful merger, new management took over and the growth started to pick up -
Production Visibility - Not a Problem. It all depends on execution.
Current Production as on FY26.
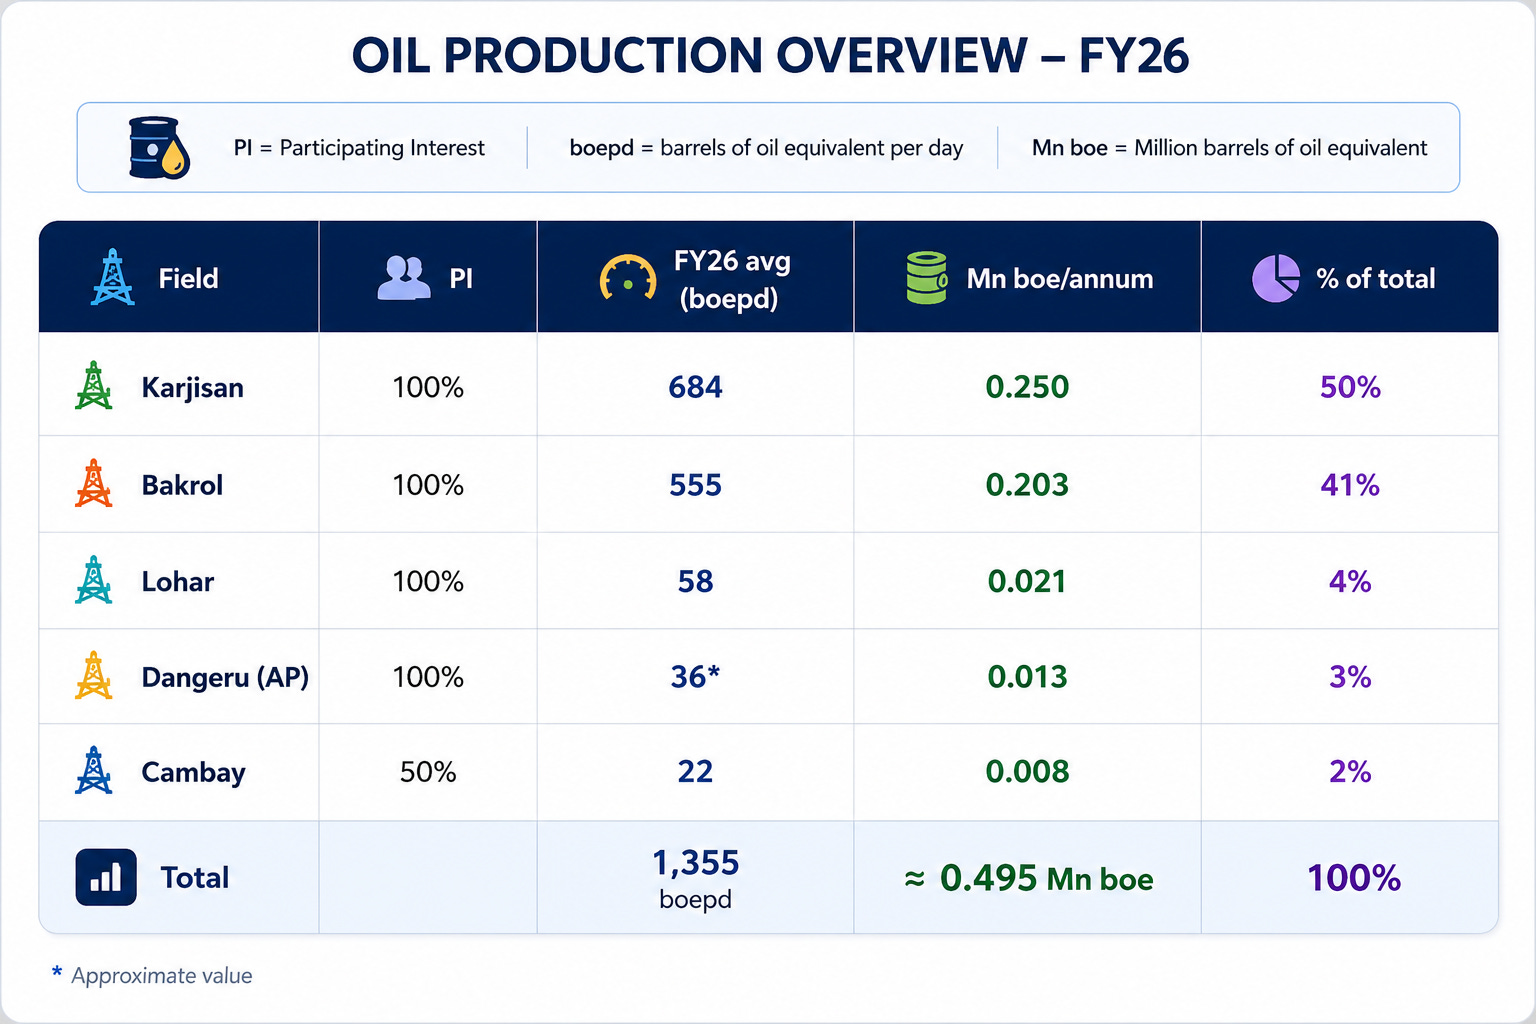
The company is currently producing mainly from Bakrol and Karjisan which are 90% of the volumes.
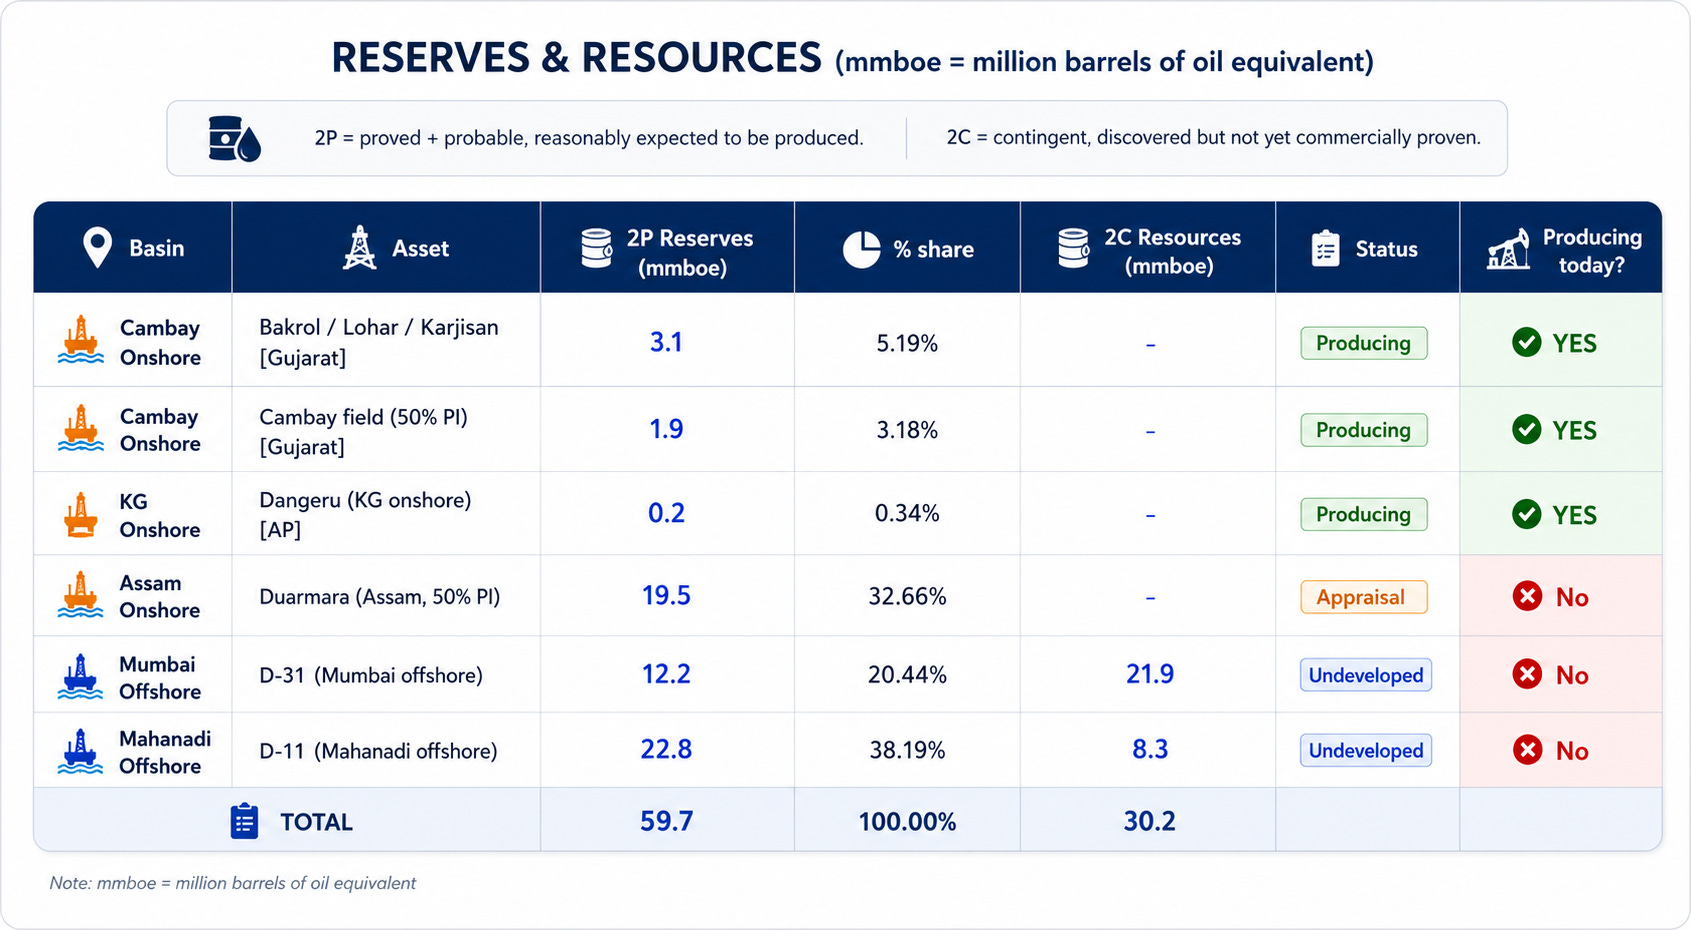
Antelopus Selan has disclosed around 60 million boe of 2P reserves. But current production for FY26 is only around 0.5 million boe annually. This creates a huge runway from other oilfields which are yet to develop in terms of production visibility but that comes with execution risk which needs to be monitored.
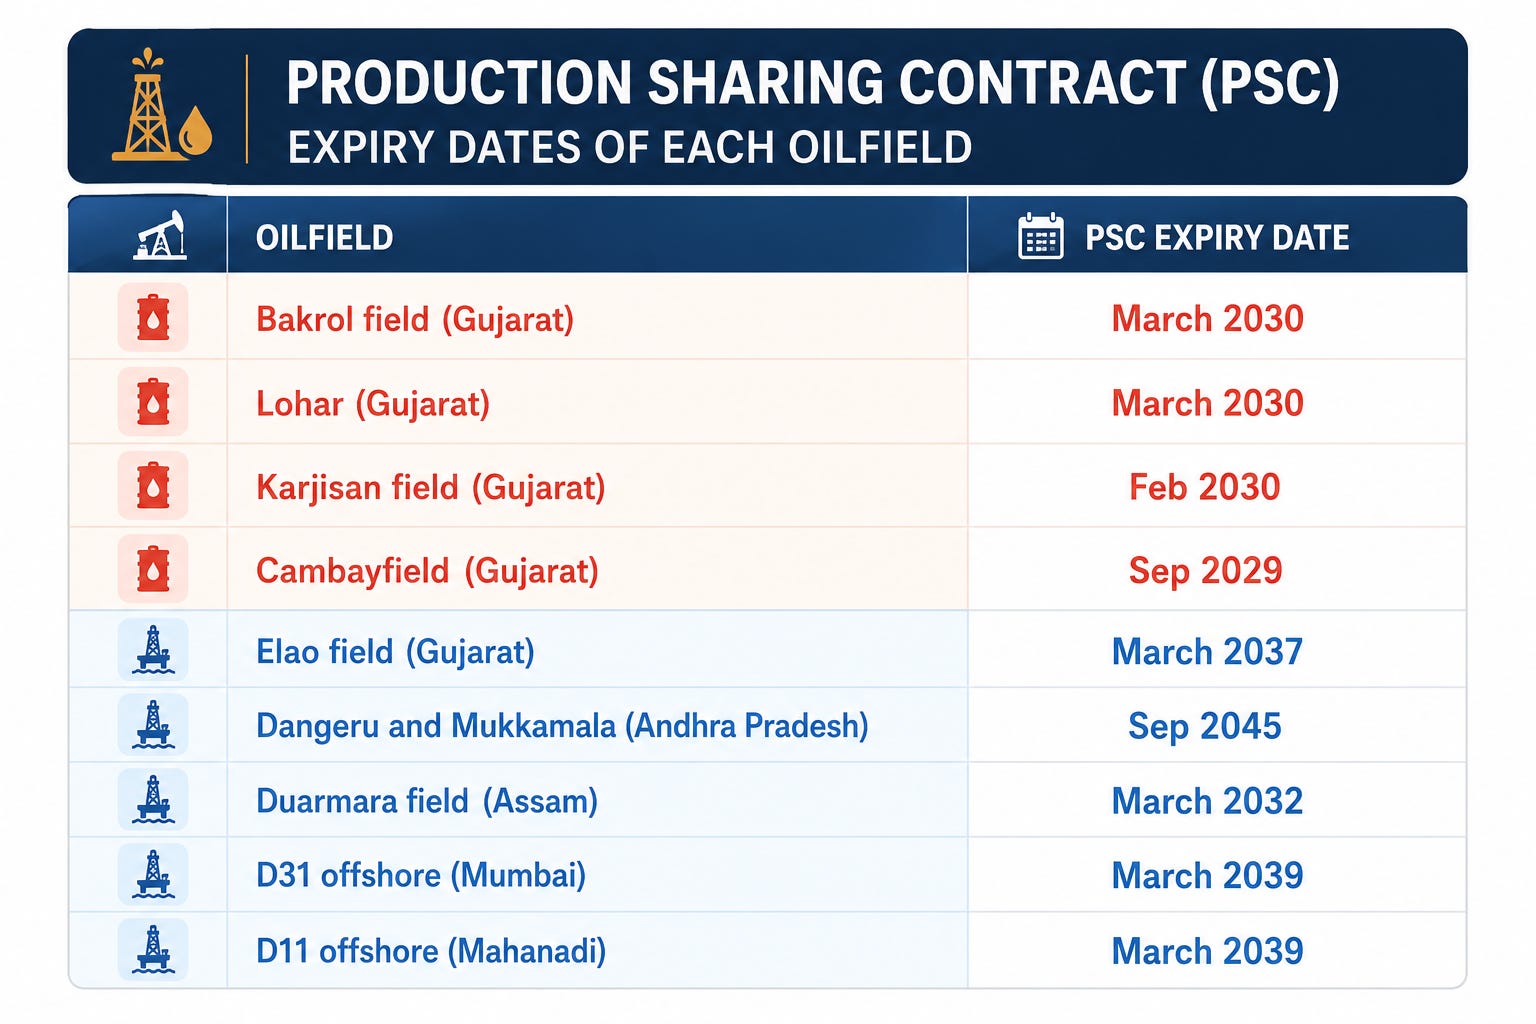
The other important risk includes - The Production Sharing Contract (PSC) for some of its very important oilfields which contribute 80-90% to its revenue are about to expire. The company has claimed for renewal of these oilfields but the status is still pending.
The Volume Composition -
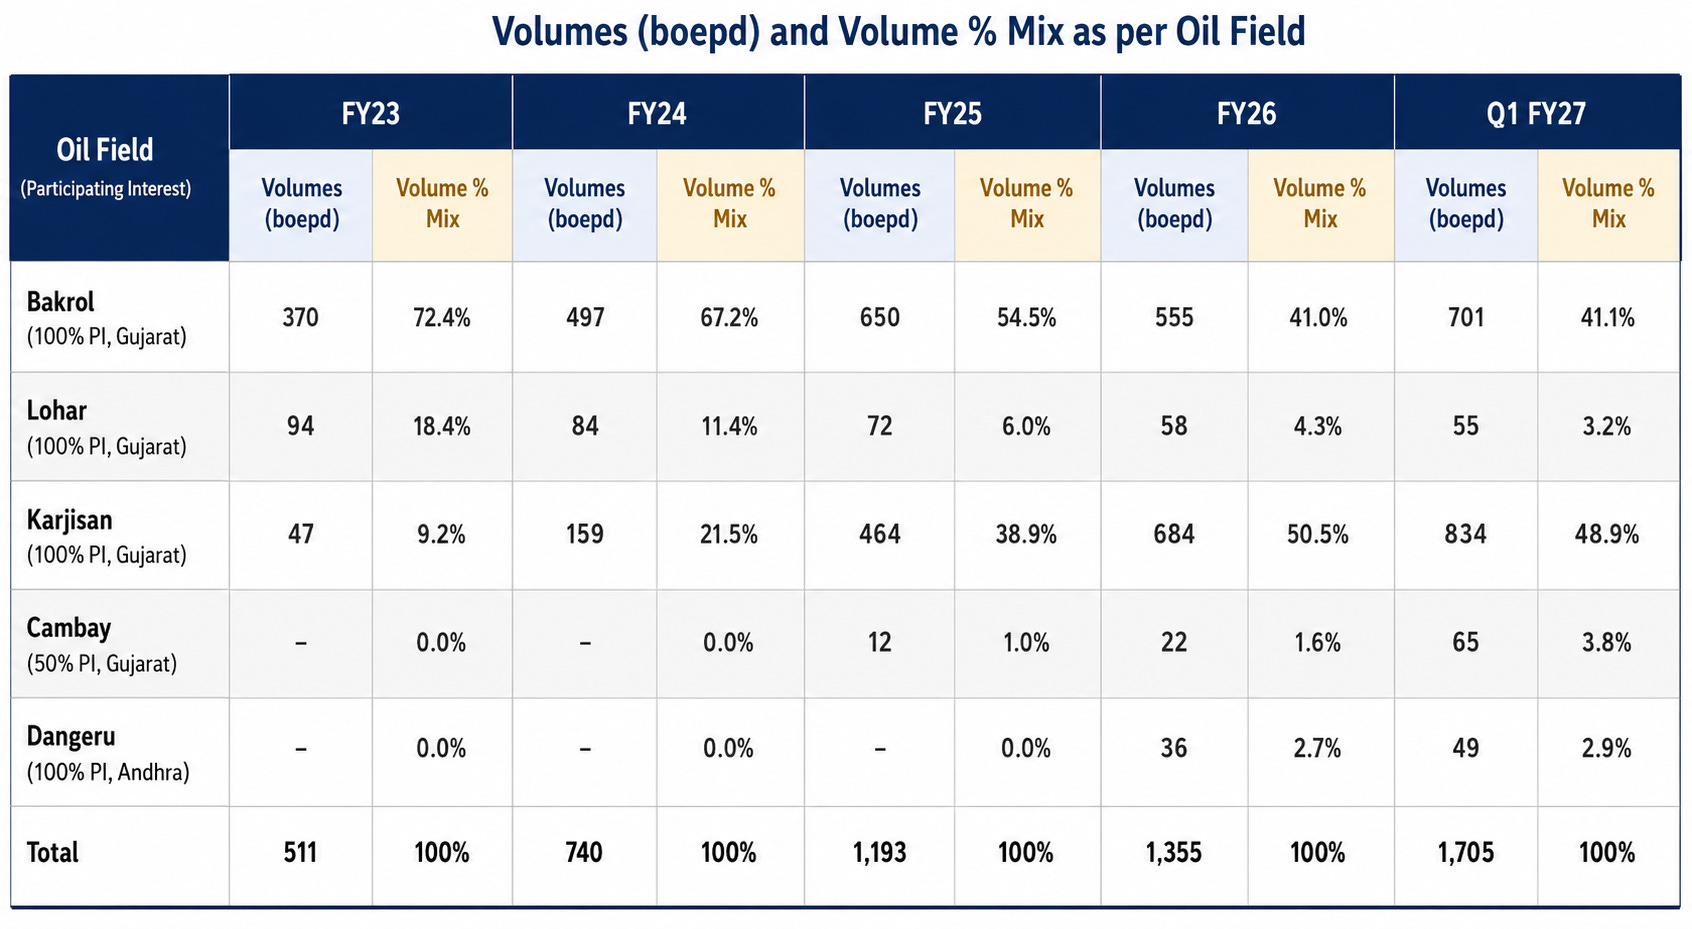
The composition shift: Bakrol used to be everything; now Karjisan is the biggest producer. Lohar is a slow, managed decline - no more drilling planned there. And two brand-new revenue streams (Cambay, Dangeru) have appeared.
In terms of revenue mix by product - As on Q1FY27, Crude oil contributes 80% of its revenue while 20% comes from Gas. It’s fundamentally an oil company with a gas kicker.
Gas prices in India are administered by the government so gas revenue is stable while oil revenue swings with Brent.
The other oil field status -
Dangeru field → First production started Aug-25. Estimate firms up with production history.
Dumara Assam → It is one-third of the reserve base - and currently underperforming. Poor injectivity, gas weaker than discovery wells.
Mumbai Offshore D-31 → 5 discoveries. Offshore development is slow and capital-hungry.
Mahanadi Offshore D11 → 6 discoveries, gas-weighted. The largest single 2P block, producing nothing.
The Near Term Growth Catalyst -
One of the clearest near-term examples is Bakrol. The company has drilled nine wells as part of its development programme. Six of these wells have already been drilled and cased but are not yet producing.
The company has already spent roughly ₹100–120 crore on these wells.
They are essentially finished holes that are currently generating no production.
The next step is hydraulic fracturing or “frac”.
In simple terms, fracturing is the process used to create or improve pathways through which oil and gas can flow towards the well.
If these wells perform as expected, production could increase without having to start the entire drilling process from scratch.
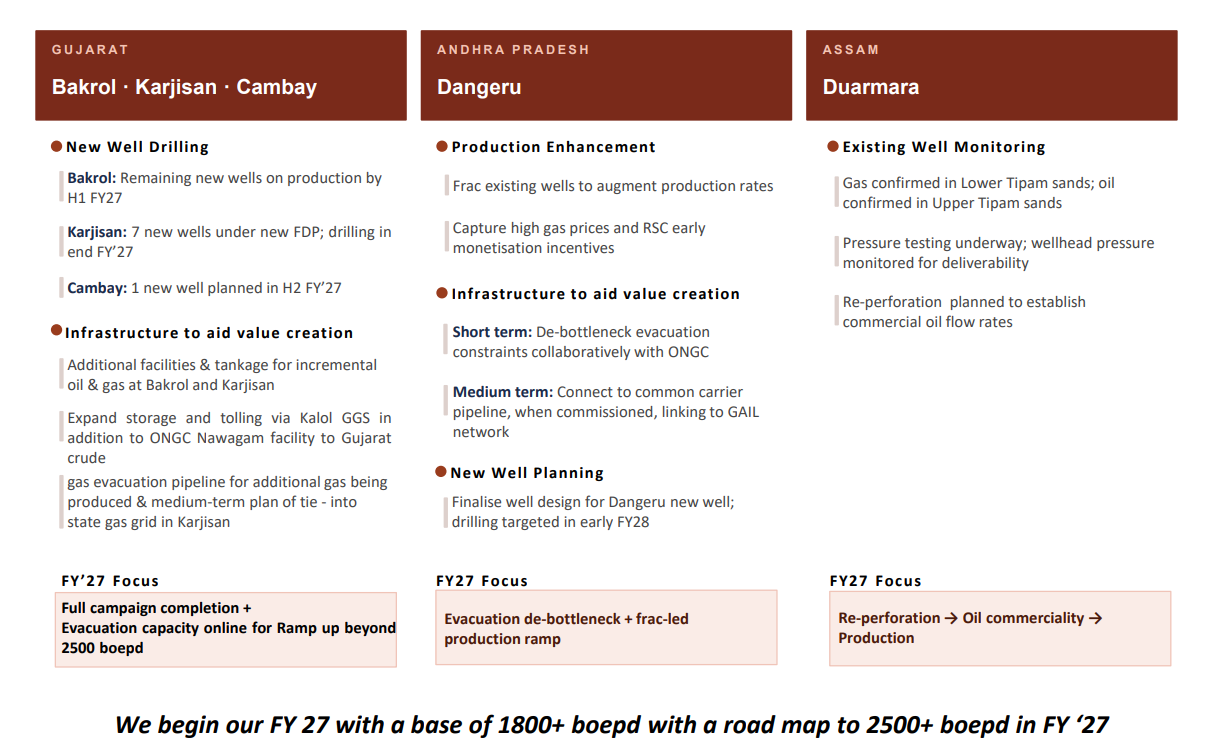
This is one of the reasons management continues to target an exit production rate of around 2,500 boepd in Q4 FY27.
The market will ultimately judge the company not by the number of wells drilled, but by how many of those wells actually start producing commercially.
FY27 Execution Focus -
Operating Leverage - An Important lever behind driving its Profits
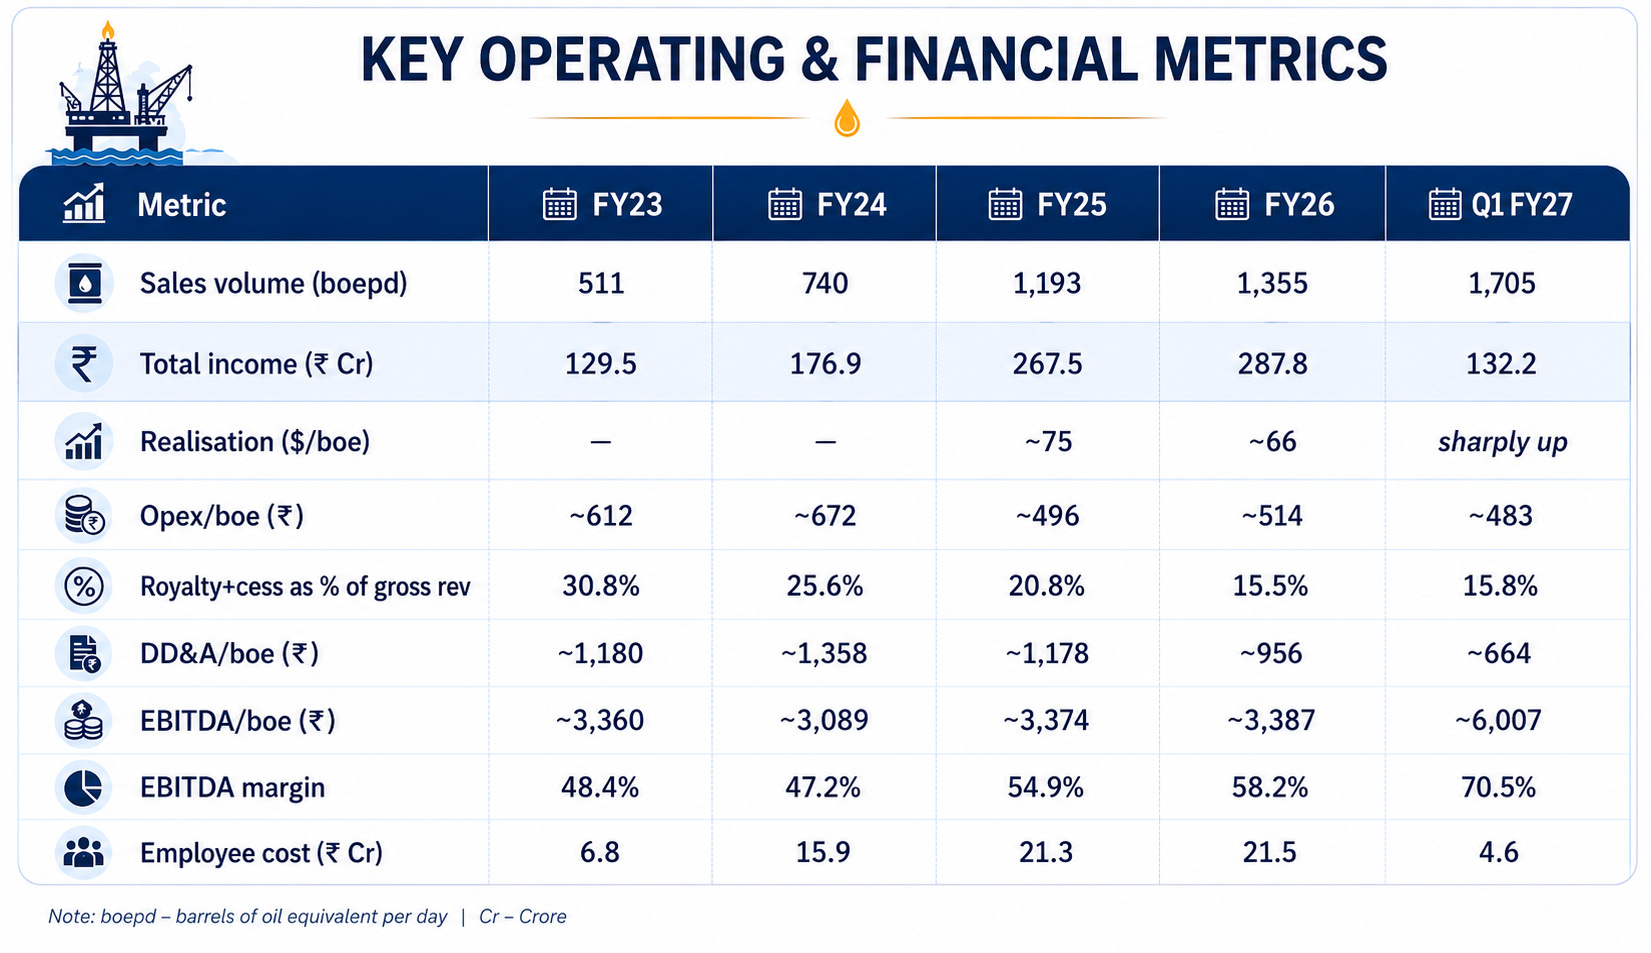
Over the last 3 years, Antelopus Selan Energy delivered 38% CAGR in Sales volumes. EBITDA margin has jumped from 48% to 58% in FY26. Margins further accelerated to 70% in the Q1 FY27 due to a sharp jump in crude oil prices on account of the US- Iran war which should not be taken as normalised margins.
Oil production has a large fixed-cost component. The company doesn’t need to double its employee costs every time production doubles.
In FY26, employee costs and other operating expenses remained broadly stable even as production increased by around 14%.This led to operating leverage.
Once the infrastructure and operating base is in place, every additional barrel can contribute disproportionately to EBITDA.
Royalty + cess is fixed on the value of sales. Price and Volume does not affect it. The recent lowering of Royalty & cess from is because of product mix change i.e Gas share rising and cess is charged on crude and not gas. Gas revenue share is currently 20% and continues to rise. Also, each oilfield has different royalty and cess. Some have higher (Pre-Nelp Oil blocks) mainly Canbay basins but the newer ones have zero cess.
The balance sheet remains strong with zero debt and ROCE of 21%. In June 2026 they got an IND A/Stable credit rating - which tells you debt capacity is now available if they want it.
But the story is not without cracks - The risk
A good oil story can quickly become a bad investment story if production doesn’t arrive. There are several things worth watching closely.
The first is execution risk -
The company’s future depends on turning discovered resources into producing assets. Duarmara oilfields has faced production challenges whereas Dangeru oilfields has started producing but remains constrained by evacuation infrastructure.
D-31 and D-11 remain undeveloped offshore assets.
The large reserve number therefore needs to be viewed as future potential, not current cash flow.
The second is capital intensity -
The company expects approximately ₹250–350 crore of capex across FY27–FY28, with the Karjisan development programme being one of the major components.
As the company moves from mature onshore assets towards offshore development, capital requirements could increase materially.
The third is field decline -
Oilfields naturally decline. Bakrol and Karjisan currently account for around 90% of production. This means the company cannot simply drill today and stop investing tomorrow.
It has to keep drilling and developing new wells to maintain and grow production.
In many ways, upstream production is a treadmill: If you stop investing, production eventually starts falling.
And finally, there is regulatory risk -
The production-sharing contracts for Bakrol, Lohar and Karjisan expire around 2030, although extensions have already been applied for but not yet granted.
The outcome and timing of these extensions remain important for the long-term value of these fields.
Conclusion -
We believe Antelopus Selan story is less about predicting the price of oil and more about watching how efficiently a management team can convert underground resources into above-ground cash flows.
The reserves provide the runway. The drilling provides the mechanism. And execution will determine how far the company actually travels.
India’s energy demand continues to rise, while the country remains heavily dependent on imports for crude oil. Increasing domestic production will not eliminate India’s dependence on imports. But every additional domestic barrel can contribute to energy security, reduce import dependence at the margin and improve utilisation of India’s domestic hydrocarbon resources. For years, India’s upstream industry has been dominated by large public-sector players. The more interesting development today is the emergence of private companies willing to invest capital, acquire producing or discovered assets and attempt to improve recovery. Antelopus Selan Energy represents one version of this transition.